If you give your child four years' worth of expenses instead of sending them to college, will that money really change their future? What determined the outcome was more than whether or not they went to college. Whether the money was paid all at once, or managed according to the purpose and stagesIt was close to .
The original text, written on September 8, 2026, presents two reconstructed cases. One child ran out of money about three years after receiving a lump sum, while the other child entered their fourth year of career after technical training, certifications, and field experience, just as their peers were starting to find employment.
The money given instead of college—what determined the outcome was the payment method.
The key point is not the cash support itself. Once you enter university, tuition is tied to semesters and the curriculum, and living expenses are used according to a set schedule, but the lump sum deposited into a bank account has no fixed timing or purpose for use.
A case was presented in which a child, who received a large sum of money all at once around the age of twenty, bought a used car and invested the money in cryptocurrencies. The content states that about three years later, as the funds were almost depleted, the child ended up with neither a degree nor any remaining assets.
Conversely, the child who received support categorized for specific purposes—such as technical training fees, certification costs, and a future shop deposit—learned auto repair and worked at a small repair shop. In this case, A structure designed to connect money with your career and the next step.made a difference in the results.
The problem is not so much the choice not to go to college, but rather the fact that the responsibility for managing the college costs is passed on to the child the moment the cost is converted into a lump sum of cash.

The cost of four years of college is insufficient if you only calculate tuition.
When parents decide not to send their child to college, the costs they calculate do not end with tuition. The actual scale of support is revealed only when housing, transportation, food, textbooks, and living expenses are added together with tuition.
The original text calculates that the combined cost of university tuition, rent, and living expenses could be close to 100 million won over four years. It states that the average tuition for a four-year university is around 7.1 million won per year, while for private universities it exceeds 8 million won per year, and mentions cases where parents send 1 million won per month in living expenses to their children attending university in Seoul.
However, even among university students, the total amount varies depending on commuting status, region, dormitory usage, and items covered by the parents. Therefore, the amount to support a child who does not attend university is not 'four years' worth of tuition,' but The amount of money required for education, living expenses, and career transition broken down by categoryIt is more realistic to calculate it as follows.

The difference between a child who received a lump sum and a child who spent it according to plan
It is difficult to attribute instances where a large sum of money disappears quickly solely to a child's personality. When suddenly acquiring a large amount of money, they may start spending on things they wouldn't normally do, or their expenses may increase as they try to appear financially well-off to those around them.
This does not mean that items like used cars or cryptocurrencies are bad. The issue lies in whether those expenses were part of the child's established career plan, and whether the structure was such that living expenses and education costs would be shaken along with any losses.
In the step-by-step support case, the child first drafted a career and financial plan, and the parents proceeded with the next stage of support after verifying processes such as completing education, preparing for certifications, and working in the field. The son, who learned automotive repair, has accumulated four years of experience at a repair shop and has made plans to open his own store based on his savings.
The purpose of the plan is not for parents to monitor their children. If you write down the duration of the education, estimated costs, the amount your child will have to pay out of pocket, and even alternatives in case the program is discontinued, the vague idea of "let's do something instead of college" turns into a concrete schedule.
Technical training, certifications, and startup support must be prioritized.
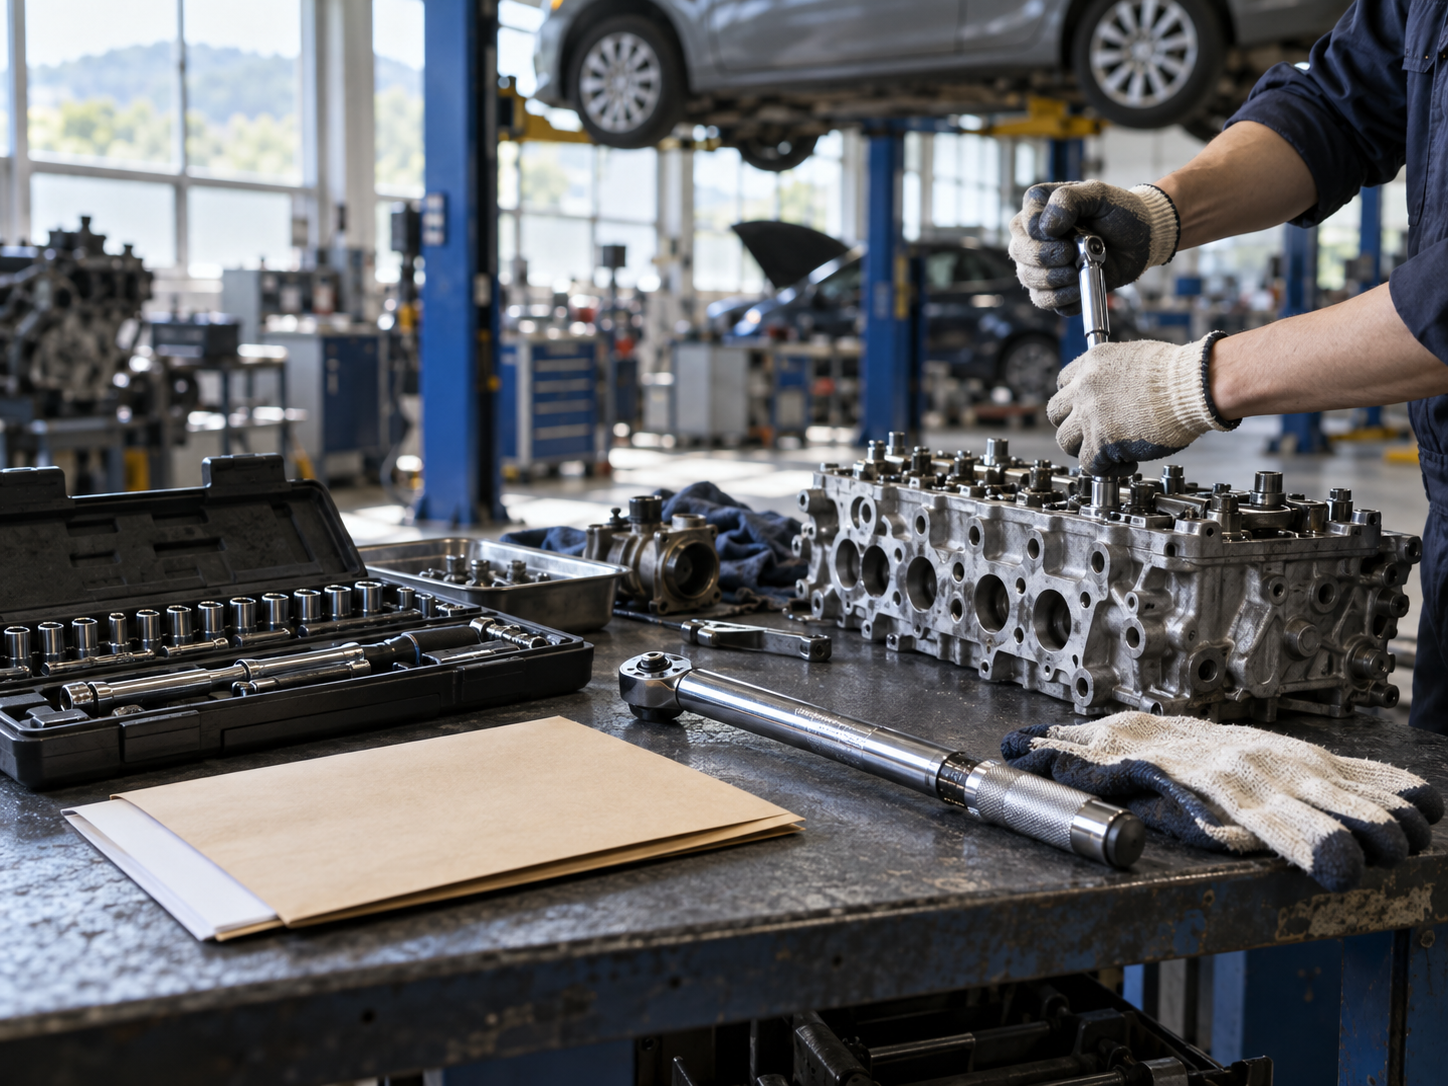
Providing startup funds immediately simply because one does not attend university places a heavy burden on them. The process of first verifying aptitude through vocational training or field experience, followed by obtaining certifications and employment, and finally considering starting a business reduces financial risk.
For example, if you choose automotive repair, tuition and tool costs are supported upfront, and certification exam fees can be set separately after the training is completed. The process involves working at an actual repair shop to experience the job aptitude and income structure, after which the shop deposit and operating funds are discussed.
For each stage, you must define not only the amount but also the duration and outcome. Instead of stating "support will be provided upon obtaining the certification," you should establish a standard such as "exam fees will be paid upon completing the designated training and submitting an exam preparation plan" so that both parents and children understand the next step.
Situations where the plan changes must be included from the beginning. If the current education is not suitable, you can switch to other vocational training, but this must be followed by a procedure to establish a new plan after reviewing the usage history of existing funds and the remaining balance.
| Support method | Key Advantages | Things to note | Suitable uses |
|---|---|---|---|
| lump-sum payment | Children can use it quickly whenever they want | Consumption and investment decisions converge all at once | If specific business or education plans already exist |
| Regular support | Easy to manage living and education expenses consistently | Support can lead to long-term dependence | Transportation, food, and tuition fees during the vocational training period |
| Step-by-step payment | The next funds can be executed in accordance with goal achievement | An agreement on standards is needed between parents and children. | Technical training, certifications, startup deposit |
When considering support for adult children, you must take into account self-reliance criteria and taxes.
Whether support helps with self-reliance or fosters dependence is revealed in the criteria rather than the amount. Temporary crises, such as sudden illness or job loss, and situations where monthly living expenses are supplemented due to a lack of consumption should not be treated as the same type of support.
If parents continuously cover all shortfalls, children have fewer opportunities to create a budget and bear the consequences of their choices. Even with monthly support, the direction of assistance changes if the child creates their own budget and sets the end date of parental support as well as the percentage they will bear.
Taxes are also difficult to overlook. As of 2026, the gift tax exemption for adult children receiving gifts from lineal ascendants, such as parents and grandparents, is set at 50 million won, and money transferred from parents to children can lead to gift tax issues depending on the relationship, the amount, and previous gift history.
‘Simply leaving a remittance note labeled 'living expenses' does not make all the money tax-exempt living expenses. Since amounts actually used for daily living may be judged differently from amounts saved in a child's name or used to acquire stocks or real estate, it is safer to record the purpose of payment and the details of usage separately when transferring large sums of money.
If you are providing financial support instead of college tuition, you should first determine the career plan, phased execution criteria, and end date of the support, rather than the size of the lump sum.
These two cases are not statistics showing the outcomes of children who do not attend college, but rather stories reconstructed to illustrate different support structures. Since college enrollment offers opportunities for degrees, curriculums, networking, and career exploration, and technical education can lead to rapid field experience and career formation, neither approach can be applied to every child.
Ultimately, if you view the money your parents would give you as "compensation for not going to college," you are likely to stop at a lump-sum payment. Career funds on how to plan the four years of your early twentiesWhen viewed this way, you can create a structure where children take direct responsibility for how money is used and the results.